Real estate investing offers several ways to make money, and fixing and flipping properties is one of the strategies many investors use to build their businesses. The process usually involves purchasing a property that needs improvements, renovating it, and selling it for a profit. However, finding the right property is only one part of a successful house flipping project. Investors also need financing that supports their purchase and renovation plans.
This is where fix and flip loans can help. These loans are designed to provide short term financing for real estate investors who want to purchase and improve investment properties. Depending on the lender and loan program, investors may be able to finance different types of residential properties and, in some cases, selected commercial or mixed use properties.
But not every property qualifies for this type of financing. Property condition, location, renovation costs, resale value, and the lender’s eligibility guidelines can all influence approval.
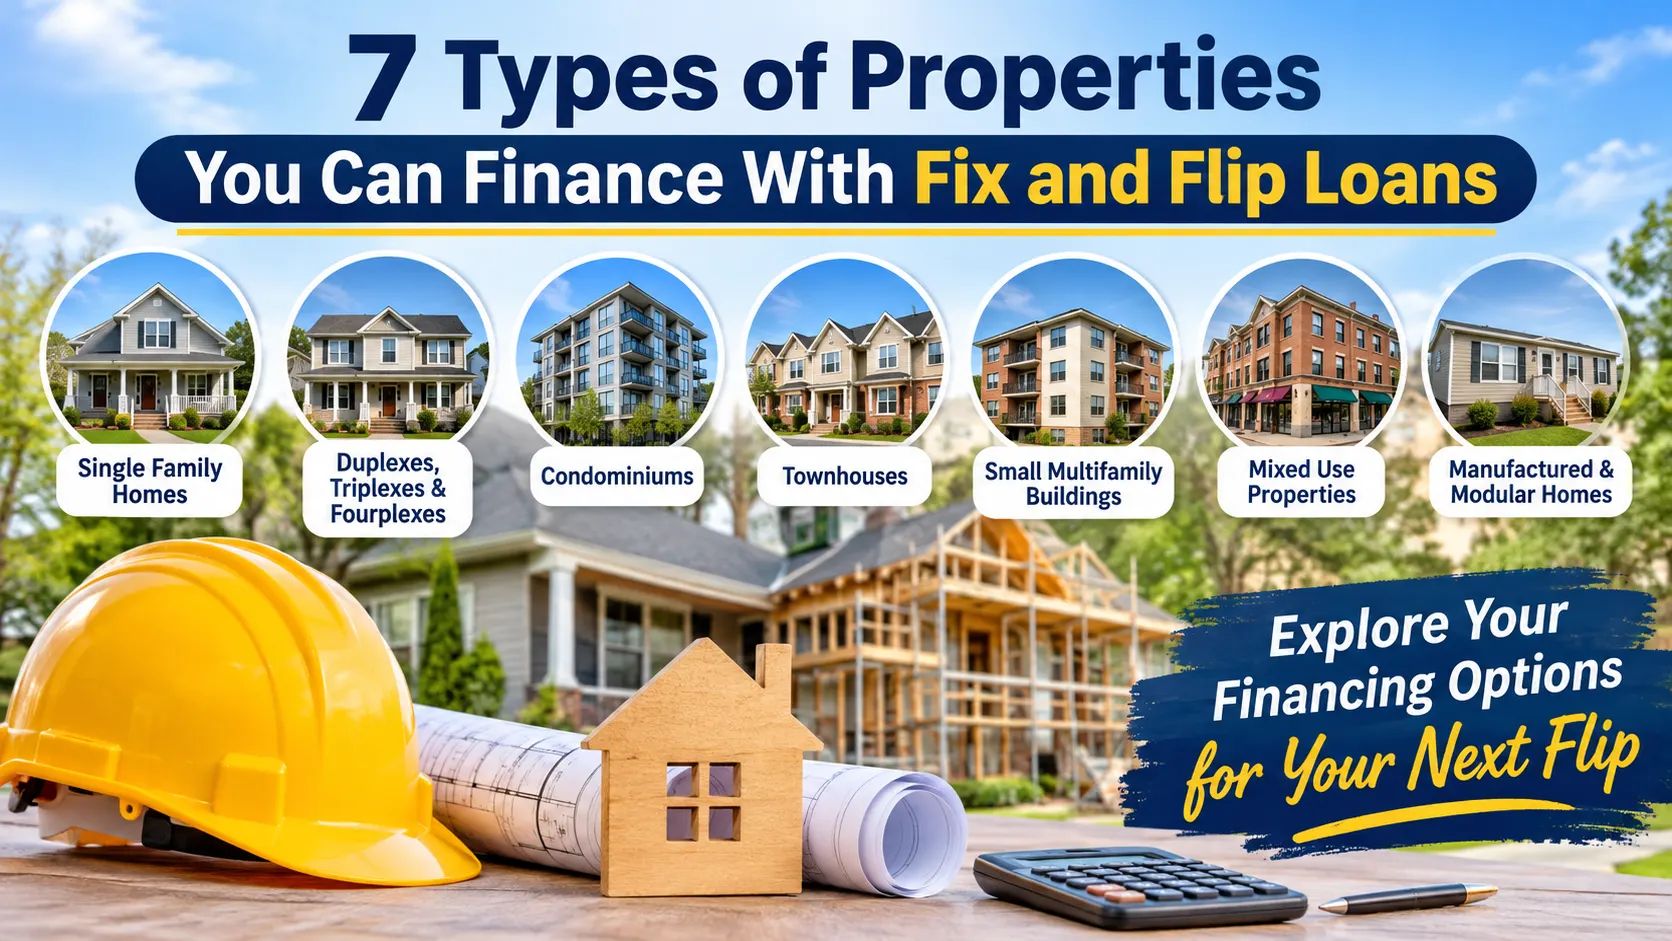
In this article, we will explore seven types of properties you may be able to finance with fix and flip loans, along with important considerations for each property type.
What Are Fix and Flip Loans?
Fix and flip loans are short term real estate investment loans used to purchase and renovate properties that investors plan to sell after completing improvements.
Unlike traditional mortgages, which are generally designed for long term homeownership, fix and flip financing focuses on the investment opportunity and the property’s potential value after renovation.
Many fix and flip financing programs can cover a portion of the property purchase price and approved renovation expenses. The exact amount depends on the property’s current value, estimated after repair value, renovation budget, borrower experience, and lender requirements.
For example, an investor may find a house selling for $180,000 that needs $40,000 in renovations. After completing the improvements, the property may have an estimated market value of $290,000.
A lender may evaluate the purchase price, renovation plan, expected resale value, and the investor’s financial position before deciding how much financing to offer.
Fix and flip loans are commonly used for non owner occupied investment properties. They are generally not intended for people purchasing a home to use as their primary residence.
7 Types of Properties You Can Finance With Fix and Flip Loans
The property types accepted by fix and flip loan lenders can vary. Some lenders focus mainly on residential properties, while others offer financing for larger or more specialized investment projects.
Here are seven property types that real estate investors may be able to finance.
1. Single Family Homes
Single family homes are among the most common property types used in house flipping projects. These properties generally have one residential unit and are designed for one household.
Investors often look for single family homes that need cosmetic improvements, outdated interiors, kitchen upgrades, bathroom renovations, or more extensive repairs.
For example, an investor may purchase an older house in a neighborhood where recently renovated homes are selling at higher prices. The investor can use financing to purchase the property, complete approved improvements, and prepare it for resale.
Single family homes can be attractive investment opportunities because their resale market is relatively straightforward in areas with consistent buyer demand.
Common renovation opportunities include:
Updating kitchens and bathrooms.
Replacing old flooring and fixtures.
Improving exterior appearance and landscaping.
Repairing roofs, windows, and plumbing.
Modernizing electrical systems and interior spaces.
Before applying for fix and flip financing, investors should consider the property’s current condition and estimated after repair value. The renovation budget should also include a reasonable allowance for unexpected repairs.
Another important consideration is the local housing market. A beautifully renovated property may still be difficult to sell if the neighborhood has limited buyer demand or comparable properties are selling slowly.
Single family homes are generally among the more widely accepted property types for fix and flip loans, although individual lender requirements still apply.
2. Duplexes, Triplexes, and Fourplexes
Multifamily properties with two to four residential units can also provide opportunities for house flipping investors.
A duplex contains two residential units, a triplex contains three, and a fourplex contains four units. These properties can attract buyers who want to live in one unit while renting out the others or investors looking for properties with multiple income opportunities.
For example, an investor may purchase a duplex with outdated kitchens, bathrooms, and common areas. After renovating both units, the investor can market the improved property to buyers interested in rental income or owner occupancy.
The ability to appeal to different types of buyers can make smaller multifamily properties interesting investment opportunities.
Renovation opportunities may include:
Updating kitchens and bathrooms in each unit.
Improving shared entrances and common areas.
Repairing plumbing and electrical systems.
Replacing old flooring and windows.
Improving parking and exterior appearance.
However, renovating a multifamily property can involve more planning than renovating a single family home.
Investors need to consider the condition of every unit, local rental demand, building safety requirements, and applicable zoning regulations.
If tenants are already occupying the property, investors should also understand existing lease agreements and applicable tenant protection laws before purchasing.
Many fix and flip loan lenders finance two to four unit residential properties. However, the lender may evaluate the entire building rather than considering each unit separately.
3. Condominiums
Condominiums can be another option for real estate investors interested in purchasing, renovating, and reselling properties.
A condominium is an individual residential unit within a larger building or community. Owners generally have responsibility for their individual units and share ownership or maintenance responsibilities for common areas through a homeowners association.
Some condos may offer attractive renovation opportunities because they have outdated interiors, older kitchens, worn flooring, or bathrooms that need improvements.
For example, an investor may purchase a condo in an established community where demand for updated units is strong. By improving the interior and making the space more appealing, the investor may be able to attract buyers looking for a move in ready property.
Common renovation opportunities include:
Replacing kitchen cabinets and countertops.
Modernizing bathrooms.
Installing new flooring.
Updating lighting and fixtures.
Improving storage and interior layouts where permitted.
However, condominiums require additional research before purchasing.
Investors should review the homeowners association rules, monthly fees, special assessments, insurance arrangements, and restrictions on renovation work.
Some communities require approval before owners can make certain improvements. Structural changes, plumbing modifications, and exterior renovations may also be restricted.
Another important consideration is the condominium association’s financial condition and the overall condition of the building.
Not all fix and flip financing programs accept condominiums. Some lenders may require the condominium project to meet specific eligibility standards.
Investors should confirm condominium eligibility with the lender before committing to a purchase.
4. Townhouses
Townhouses are residential properties that usually share one or more walls with neighboring homes. They may be located in planned communities or residential developments.
These properties can appeal to buyers who want more living space than an apartment but prefer a smaller property with less exterior maintenance than a detached house.
Older townhouses may need interior upgrades, improved layouts, modern fixtures, or exterior maintenance. Investors can purchase these properties at an attractive price when the renovation costs and potential resale value support the investment.
For example, an investor may purchase an older townhouse with outdated bathrooms, damaged flooring, and an aging kitchen. After completing the improvements, the investor can market the property to buyers looking for updated housing in the same neighborhood.
Potential renovation projects include:
Modernizing kitchens and bathrooms.
Replacing flooring and interior doors.
Improving lighting and storage.
Updating heating and cooling systems.
Improving permitted exterior features.
One important difference between townhouses and detached homes is shared ownership or maintenance responsibilities in some communities.
Before purchasing, investors should review association requirements, renovation restrictions, shared maintenance responsibilities, and applicable property rules.
Townhouses are accepted by many fix and flip financing programs, but approval depends on the property structure, ownership arrangement, community restrictions, and lender guidelines.
5. Small Multifamily Apartment Buildings
Some fix and flip loan lenders also consider larger multifamily properties containing five or more residential units.
These properties are different from duplexes, triplexes, and fourplexes because they generally involve more complex renovation and management requirements.
For example, an investor may purchase a small apartment building with several vacant units, outdated common areas, and aging building systems.
The renovation project could involve updating individual apartments, improving hallways, repairing plumbing, replacing roofing, or upgrading shared facilities.
After completing the improvements, the investor may sell the property to another investor or a buyer interested in operating a multifamily rental business.
Common improvement opportunities include:
Renovating individual apartment units.
Improving shared hallways and entrances.
Upgrading plumbing and electrical systems.
Repairing roofing and exterior structures.
Improving parking and shared facilities.
Multifamily renovations require careful financial planning. Investors need to evaluate the condition of the entire building, not just individual apartments.
They should also consider local rental demand, occupancy levels, operating expenses, property taxes, insurance, and applicable building regulations.
Financing availability is particularly important for this property type. Some fix and flip lenders limit their programs to residential properties with one to four units. Others may consider larger multifamily projects under specialized financing programs.
Investors should discuss the property size, renovation scope, and proposed exit strategy with lenders before making an offer.
6. Mixed Use Properties
Mixed use properties combine residential and commercial spaces within the same building or development.
For example, a building may have retail space on the ground floor and apartments on the upper floors. Another property may combine office space with residential units.
These properties can provide interesting opportunities for investors who understand both residential and commercial real estate markets.
An investor might purchase an older mixed use building with vacant residential units, outdated retail space, and a property exterior that needs improvements.
The renovation could involve modernizing the apartments, improving the commercial frontage, updating building systems, and making common areas more attractive.
Potential renovation opportunities include:
Updating residential units.
Improving retail storefronts.
Repairing shared building systems.
Modernizing entrances and common areas.
Improving the property’s overall appearance.
However, mixed use properties usually involve more complex underwriting than standard residential properties.
Lenders may evaluate the percentage of residential and commercial space, property zoning, occupancy, building condition, and the expected resale market.
Investors should also understand the local rules governing commercial and residential uses.
Not all fix and flip financing programs cover mixed use properties. Some lenders may require a specific percentage of the building to be residential, while others may offer separate commercial financing options.
If you are considering this type of investment, confirm the lender’s property eligibility requirements before proceeding.
7. Manufactured and Modular Homes
Manufactured and modular homes can also offer renovation opportunities for investors, although financing eligibility is more limited than for conventional single family properties.
Manufactured homes are built in a factory and transported to their installation location. Modular homes are also constructed in sections at a factory but are assembled on a permanent foundation according to applicable building codes.
Both property types may require improvements before they are ready for resale.
For example, an investor may find an older manufactured home that needs interior updates, flooring replacement, roofing repairs, or improvements to its exterior appearance.
After completing the renovation, the investor may be able to sell the property to buyers looking for affordable housing.
Possible renovation opportunities include:
Replacing outdated flooring and fixtures.
Updating kitchens and bathrooms.
Repairing roofs and exterior siding.
Improving heating and cooling systems.
Modernizing interior spaces.
However, investors should pay close attention to the property’s ownership and installation details.
The lender may want to know whether the home is permanently attached to land, whether the land is owned or leased, whether the foundation meets applicable requirements, and whether the property has the necessary documentation.
Age, condition, title status, and local building regulations may also affect financing eligibility.
Some fix and flip loan lenders accept certain manufactured or modular homes, while others restrict their programs to conventional residential properties.
For this reason, investors should verify eligibility before purchasing the property.
What Do Fix and Flip Loan Lenders Consider Before Financing a Property?
Choosing the right property is important, but investors should also understand how lenders evaluate a potential project.
Although lending requirements vary, several factors commonly influence financing decisions.
1. Property Condition
Lenders review the property’s current condition to understand the repairs and improvements needed.
They may consider structural problems, roof damage, plumbing issues, electrical systems, water damage, and other major concerns.
A property requiring extensive structural repairs may need additional review or may fall outside a lender’s standard program.
2. After Repair Value
After repair value, commonly called ARV, is the estimated market value of a property after approved renovations are completed.
Lenders may use ARV when determining how much financing they are willing to provide.
For example, if a property is expected to be worth $300,000 after renovations, the lender may evaluate whether the purchase price and renovation budget support that estimated value.
Comparable property sales, local market conditions, and the renovation plan can influence the valuation.
3. Renovation Budget
Investors generally need to provide a clear renovation plan and cost estimate.
This helps the lender understand what improvements are planned and how much money may be required.
A detailed budget should include materials, labor, contractor expenses, permits, and a reasonable contingency for unexpected repairs.
4. Borrower Experience
Some lenders consider an investor’s previous experience with property renovations and completed real estate projects.
However, first time investors may also qualify with certain programs.
The lender may place greater importance on the investment opportunity, financial reserves, renovation plan, and the borrower’s ability to complete the project.
5. Location and Resale Demand
A property located in an area with consistent buyer demand may present a stronger investment opportunity.
Lenders may review comparable sales, neighborhood conditions, property values, and the expected time required to sell the renovated property.
Investors should research the local market before purchasing a property rather than relying only on projected resale prices.
How to Choose the Right Property for Fix and Flip Financing
Not every property that looks inexpensive is a good investment. Before purchasing a property, investors should evaluate whether the renovation project makes financial sense.
Here are some important steps to consider.
Understand the local market. Research recently sold properties in the same neighborhood. Compare property sizes, features, condition, and selling prices.
Estimate renovation expenses carefully. Obtain contractor estimates and account for permits, materials, labor, and unexpected repairs.
Calculate the potential profit. Include the purchase price, renovation expenses, financing costs, property taxes, insurance, utilities, and selling expenses.
Check property eligibility. Confirm that the lender accepts the property type and location before making a purchase commitment.
Prepare a clear exit strategy. Understand who the potential buyers are and whether the renovated property can realistically sell within the expected loan term.
Review financing terms. Compare interest rates, origination fees, repayment terms, renovation draw procedures, and extension options.
A well researched purchase can help investors avoid unnecessary expenses and improve their chances of completing a successful project.
Conclusion
Fix and flip loans can provide financing opportunities for several types of real estate investment properties. Single family homes, smaller multifamily properties, condominiums, townhouses, and certain larger or specialized properties may qualify depending on the lender’s guidelines.
The most important step is to understand the property’s condition, renovation requirements, potential after repair value, and resale demand before applying for financing.
Investors should also work with experienced fix and flip loan lenders who understand their investment goals and can explain the available financing options.
At Simplending Financial, investors can explore financing options for eligible fix and flip investment projects. Understanding your property and renovation plans can help determine which financing solution may be appropriate for your next investment.
Frequently Asked Questions About Fix and Flip Loans
1. What types of properties qualify for fix and flip loans?
Fix and flip loans may be available for single family homes, duplexes, triplexes, fourplexes, condominiums, townhouses, and certain multifamily or mixed use properties. Some specialized programs may also consider manufactured and modular homes. Eligibility depends on the lender, property condition, location, and loan program.
2. Can you use fix and flip loans to purchase a multifamily property?
Yes. Some lenders offer fix and flip financing for multifamily investment properties. Properties with two to four units are accepted by many programs, while buildings with five or more units may require specialized financing. Investors should confirm the lender’s unit limits before applying.
3. Can I get a fix and flip loan for a condominium?
Yes, some lenders finance condominiums through fix and flip loan programs. However, they may review the condominium association, building condition, insurance, ownership arrangements, and renovation restrictions before approving the property.
4. Can fix and flip loans finance properties that need major repairs?
Some fix and flip financing programs accept properties requiring significant repairs. However, major structural problems, foundation damage, extensive water damage, or serious safety concerns may require additional underwriting or may make a property ineligible.
The lender generally reviews the renovation scope, estimated costs, property value, and overall investment feasibility.
5. Can I use a fix and flip loan for a property I plan to live in?
Generally, no. Fix and flip loans are designed for business purpose real estate investments rather than primary residences. Investors purchasing a property to renovate and resell should confirm the occupancy requirements of their chosen loan program.
6. Do fix and flip loan lenders finance mixed use properties?
Some lenders offer financing for mixed use properties that combine residential and commercial spaces. However, eligibility depends on the residential and commercial space distribution, property condition, zoning, and lender guidelines. Some lenders may require a specialized commercial financing program.
7. Can first time investors qualify for fix and flip loans?
Yes. Some fix and flip lenders work with first time real estate investors. However, approval may depend on the property’s investment potential, renovation budget, financial reserves, credit profile, and the borrower’s ability to complete the project.
8. How much of the property purchase and renovation costs can fix and flip loans cover?
The amount varies by lender and loan program. Some lenders finance a portion of the purchase price and approved renovation costs, subject to maximum loan to cost and after repair value limits. Borrowers generally need to contribute some of their own funds toward the investment.
9. Can I get fix and flip financing for a foreclosed property?
Yes. Some fix and flip loan programs allow investors to finance eligible foreclosed properties. The lender will generally review the property’s condition, purchase price, estimated renovation costs, and potential resale value. Investors should also check the property’s title and any outstanding liens before closing.
10. What should I check before applying for fix and flip financing?
Before applying, investors should understand the property purchase price, renovation budget, estimated after repair value, local resale demand, and expected project timeline. They should also prepare relevant property documents, contractor estimates, financial information, and a clear exit strategy.
Join the conversation